


Loblaw is a scam. Everything is so expensive there. I don't even know why people shop there.
Because they'd rather pay a premium to avoid shopping with riff raff.
#Truth


Loblaw is a scam. Everything is so expensive there. I don't even know why people shop there.
That's why I shop at No Frills and use the card there.
Loblaw is a scam. Everything is so expensive there. I don't even know why people shop there.

That's why I shop at No Frills and use the card there.
I see your point, but the exorbitant prices bother me much more than the "riff raff".Because they'd rather pay a premium to avoid shopping with riff raff.
#Truth
The only way you accumulate points at No Frills is if you pay with a PC Financial MasterCard. They will ask you for your points card but if you pay with cash or debit, you won't receive any points.
If you cancel a card this will bring down your credit score.
What's the rationale/logic behind this?
you are wrong - I collect points at NoFrills all the time...
While you may collect points on special offers, it's not like it was before where you would get points for every dollar spent. Read the bottom of your receipt next time you pay with cash or debit. It tells you how many points you would've collected had you paid with a PC MasterCard. Same thing applies at Loblaws.
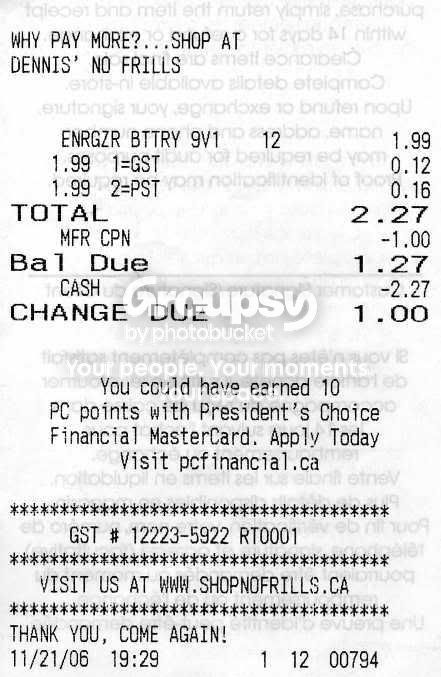
This is what you will see at the bottom of your receipt when you scan your PC Optimum card and pay with cash or debit.
Example : If you have 2 credit cards with $5,000. credit limit on each, you have a total credit of $10,000. available to you. Should you cancel one card, now you have only $5000. credit available to you. Your credit score dropped because you now only have half the credit worthiness of when you had 2 cards.
So are you saying that if you pay with the PC MasterCard you won't get the special offer points?
No... If you pay with your PC MasterCard you will get points on both "your offers" and any other items. If you're paying by cash or debit you'll only get points on the "your offers" items and no points on anything else. That's why the message at the bottom about the points you could've earned.
It was always that way.
I am just trying to understand - having more cards or more credit limit enhance the credit score?
Nope... When it was PC Points before it merged with Optimum, you would earn points on every dollar spent at No Frills and Loblaws, regardless of method of payment. In order to earn point on every dollar, now you have to pay with a PC MasterCard.
Yes, each time you apply for credit the store/business/bank does a credit check on you. If you are approved for a line of credit or credit card your credit score is raised. There are other factors that effect your credit score . If you carry a high balance or do not pay off your credit card on time your score is lowered. If you have a court judgement against you, have a credit card put into collection or have a seizure on your bank account or property this will lower your credit score as well.
That is not true.
Sorry but it is not. Having multiple cards can actually bring your credit rating down. So can having cards that you don't use. Canceling a card does not lower your rating unless it is something to with bankruptcy. Not just canceling because you don't use it. As again, having an unused card can negatively affect your credit rating.
There is a income to credit ratio you completely missing.
People loooing at their credit rating and what affects it and what doesn't, should rely on actual banks and credit unions telling you what's up. Not people like this on TERB.
Yes, each time you apply for credit the store/business/bank does a credit check on you. If you are approved for a line of credit or credit card your credit score is raised. There are other factors that effect your credit score . If you carry a high balance or do not pay off your credit card on time your score is lowered. If you have a court judgement against you, have a credit card put into collection or have a seizure on your bank account or property this will lower your credit score as well.
That is not true.
Sorry but it is not.
Quote : Having several credit cards, in and of itself, does not hurt your credit score. What matters are the specifics of those cards and how you have used them.Having multiple cards can actually bring your credit rating down.
Your credit score is roughly based on five factors, some of which are weighted more heavily than others:
Types of credit in use: 10%
New credit: 10%
Length of credit history: 15%
Amounts owed (and amounts available): 30%
Payment history: 35%
https://www.investopedia.com/ask/an...several-credit-cards-hurt-my-credit-score.asp
Quote : Having the credit available but unused is tremendously valuable to your score. Since "they" are judging how much of your available credit you are using, you should do what you can to "keep the cards alive" without adversely affecting your credit-to-debt ratio.So can having cards that you don't use.
https://www.creditkarma.com/questio...should-i-cancel-them-or-will-that-hurt-my-cre
Quote : If you’re thinking about cleaning up your credit report by closing a credit card account you haven’t used for years, you’ll probably want to reconsider that plan. That’s because closing a credit card account can actually lower your credit score. How? First, by potentially reducing the length of your credit history, especially if you’ve had the account for a long time, and second, by reducing your available credit.Canceling a card does not lower your rating unless it is something to with bankruptcy.
https://www.credit.com/credit-scores/does-closing-credit-card-account-affect-credit-score/
It is not income to credit ratio that is a consideration for credit, it is Debt-to-Credit Ratio.There is a income to credit ratio you completely missing.
a person with high income can be amazingly careless with credit while another person with low or moderate income can be incredibly efficient with credit.
People loooing at their credit rating and what affects it and what doesn't, should rely on actual banks and credit unions telling you what's up. Not some ( I change it for you ) people like this on TERB.


