

I go to the bank the other day to pay off some credit cards after a trip to the States. Actually, one card I did not use as it has a high limit and is only for emergencies. The other card is going to have a small amount owing. I pay it off and then as I am about to leave, the teller warns me that there is $4100.00 owing on the other card. What? I have not used this card in six months. That is not my charge! To make a long story short, the bank produced an image of a generic Bank of Nova Scotia cheque, printed in french, dated within the last two weeks, drawn on my bank in this amount with my name (incorrect) printed in the upper left hand corner with my address (accurate), my name, incorrect again, printed, not signed, on the signature line and had my credit card no. on the notes line. It had been processed at a CIBC. branch. The bank manager thinks that it had been put through an ATM. How can the bank let this get past them? Why did Visa not call me as there was clearly unusual activity on the card? Is it really that easy to do this kind of thing? How did someone get my card no. especially since I have not used it in such a long time? The only person who has access to it is my GF. and I know she is not involved. This is my first foray into the world of fraud and identity theft. Anyone have any insight into this kind of thing?
You are using an out of date browser. It may not display this or other websites correctly.
You should upgrade or use an alternative browser.
You should upgrade or use an alternative browser.


Fraud - Some Insight?
- Thread starter Mable
- Start date
Youch. Other than contact the cops right away (And I assume you did), and don't let the bank try and lay ANY of the blame on you, I got nothing. Seems pretty clear cut that they and/or the CIBC are the ones that fucked up, so I wouldn't worry too hard. They'll track the account that cashed it and with luck catch whoever did this. Even if they don't catch them, they are still obliged to credit your account with the amount that was taken off. Do keep us posted!I go to the bank the other day to pay off some credit cards after a trip to the States. Actually, one card I did not use as it has a high limit and is only for emergencies. The other card is going to have a small amount owing. I pay it off and then as I am about to leave, the teller warns me that there is $4100.00 owing on the other card. What? I have not used this card in six months. That is not my charge! To make a long story short, the bank produced an image of a generic Bank of Nova Scotia cheque, printed in french, dated within the last two weeks, drawn on my bank in this amount with my name (incorrect) printed in the upper left hand corner with my address (accurate), my name, incorrect again, printed, not signed, on the signature line and had my credit card no. on the notes line. It had been processed at a CIBC. branch. The bank manager thinks that it had been put through an ATM. How can the bank let this get past them? Why did Visa not call me as there was clearly unusual activity on the card? Is it really that easy to do this kind of thing? How did someone get my card no. especially since I have not used it in such a long time? The only person who has access to it is my GF. and I know she is not involved. This is my first foray into the world of fraud and identity theft. Anyone have any insight into this kind of thing?
That's weird that you weren't contacted. Twice now I've had Visa contact me when someone attempted to use my card number, once within twenty minutes of the transaction! The other time occured when I was on vacation. They actually arranged it so only transactions in the city where I was visiting would be allowed and only up to a certain limit until I got home.
It was a CIBC one, they have always been very good to me.
It was a CIBC one, they have always been very good to me.
Yeah the Banks are usually very vigilant on any unusual activity on credit cards because they're a primary target for scammers. Typically your Bank should have returned the item as fraudulent to be charged back to the account where it was deposited. Of course the chances of an active account with funds available now is nil. So the two Banks have to determine who's absorbing the loss. Normally there are timelines for chargebacks to be made of just a day or two but I believe this does not apply in cases of fraud. Your visa account should be credited back immediately though.
If you notified the proper people right away, then I'd say you've done your part. A few years ago I found a charge on my card that wasn't mine- over $1000 for a plane ticket. I told the bank (CIBC) right away and they dropped the charge, cancelled my card and issued a new one, and said they'd investigate the matter. My only cost was the hassle of updating my card info with the few charities that charge my card for monthly donations.
Your case sounds like a few people were asleep at the switch. I've had calls from my bank when I've made large purchases that don't fit with my usual spending. Being watched by big business can sometimes be a good thing.
Your case sounds like a few people were asleep at the switch. I've had calls from my bank when I've made large purchases that don't fit with my usual spending. Being watched by big business can sometimes be a good thing.
Too vigilant by half. I had an elderly relative have his card denied while driving to Mexico because the banks/CC companies thought it was mighty suspicious that a Canadian's credit card was being used to buy gas somewhere in the southwestern US. Motherfuckers wrecked an old man's vacation.Yeah the Banks are usually very vigilant on any unusual activity on credit cards because they're a primary target for scammers.
Too vigilant by half. I had an elderly relative have his card denied while driving to Mexico because the banks/CC companies thought it was mighty suspicious that a Canadian's credit card was being used to buy gas somewhere in the southwestern US. Motherfuckers wrecked an old man's vacation.
Couldn't he call from Mexico to notify them of his trip?
It is now common practice for CC cos. to freeze an account if there's a foreign transaction without notice by the cardholder of the particular trip.
Too vigilant by half. I had an elderly relative have his card denied while driving to Mexico because the banks/CC companies thought it was mighty suspicious that a Canadian's credit card was being used to buy gas somewhere in the southwestern US. Motherfuckers wrecked an old man's vacation.
Actually it's good business practice on their part. It's very easy to prevent this. I just call them the day before my vacation and give them my itinery including airports. That's how they knew my card was illegally used in Toronto when I was away and accommodated me by keeping it active as I outlined.
With the amount of fraud going on I small amount of due diligence on cardholders part can prevent a lot.
I go to the bank the other day to pay off some credit cards after a trip to the States. Actually, one card I did not use as it has a high limit and is only for emergencies. The other card is going to have a small amount owing. I pay it off and then as I am about to leave, the teller warns me that there is $4100.00 owing on the other card. What? I have not used this card in six months. That is not my charge! To make a long story short, the bank produced an image of a generic Bank of Nova Scotia cheque, printed in french, dated within the last two weeks, drawn on my bank in this amount with my name (incorrect) printed in the upper left hand corner with my address (accurate), my name, incorrect again, printed, not signed, on the signature line and had my credit card no. on the notes line. It had been processed at a CIBC. branch. The bank manager thinks that it had been put through an ATM. How can the bank let this get past them? Why did Visa not call me as there was clearly unusual activity on the card? Is it really that easy to do this kind of thing? How did someone get my card no. especially since I have not used it in such a long time? The only person who has access to it is my GF. and I know she is not involved. This is my first foray into the world of fraud and identity theft. Anyone have any insight into this kind of thing?
We've had fraudsters create counterfeit company cheques probably stolen in the mail, and cashed them. The bank didn't tell me until I learned later (they don't want to reveal loopholes) that such cheques can be deposited and cashed at an ATM, since it takes 3 days for the ATM staff to physically review the cheque's validity. The criminal would have to set up an account, and probably did so with a phony I.D.
We've even seen a trade name registered that is similar to our corporate name but not quite. We found out by an accidental search for a new business name, then sent out a cease and desist letter. It is one way for criminals to deposit stolen corporate cheques in the mail, assuming the bank teller doesn't pick up slight variations in a business name.
Couldn't he call from Mexico to notify them of his trip?
It is now common practice for CC cos. to freeze an account if there's a foreign transaction without notice by the cardholder of the particular trip.
Actually it's good business practice on their part. It's very easy to prevent this. I just call them the day before my vacation and give them my itinery including airports. That's how they knew my card was illegally used in Toronto when I was away and accommodated me by keeping it active as I outlined.
With the amount of fraud going on I small amount of due diligence on cardholders part can prevent a lot.
And why the fuck should the onus be on him? If he is going on a trip, he shouldn't have to call and notify anyone, he should be able to just go and use his goddamned credit card the way it is supposed to be used. All this overly eager fraud prevention exists merely to serve the credit card companies, NOT their customers. "Covering your ass" is not necessarily the same as "good business practice", especially when it alienates and dicks over an elderly customer.
And why the fuck should the onus be on him? If he is going on a trip, he shouldn't have to call and notify anyone, he should be able to just go and use his goddamned credit card the way it is supposed to be used. All this overly eager fraud prevention exists merely to serve the credit card companies, NOT their customers. "Covering your ass" is not necessarily the same as "good business practice", especially when it alienates and dicks over an elderly customer.
Dude. That's the way it is. So you can either go Archie Bunker and be unhappy or make an simple phone call, preventing all the hassle. It's unfortunate that a bit of inconvenience is required to prevent greater hassle and stop criminal activity is needed but really.......
Is it that big a deal?
Damned right it is. I have a credit card. I signed up for one with the understanding that it was going to make it easier for me to make purchases, not harder. Then, somewhere around 15 - 20 years ago, some of their bean counters realised that they could lose fewer beans if they shut my credit card down for "suspicious activity". They even did a cute-funny ad campaign to get the mouth breathers on side:Dude. That's the way it is. So you can either go Archie Bunker and be unhappy or make an simple phone call, preventing all the hassle. It's unfortunate that a bit of inconvenience is required to prevent greater hassle and stop criminal activity is needed but really.......
Is it that big a deal?
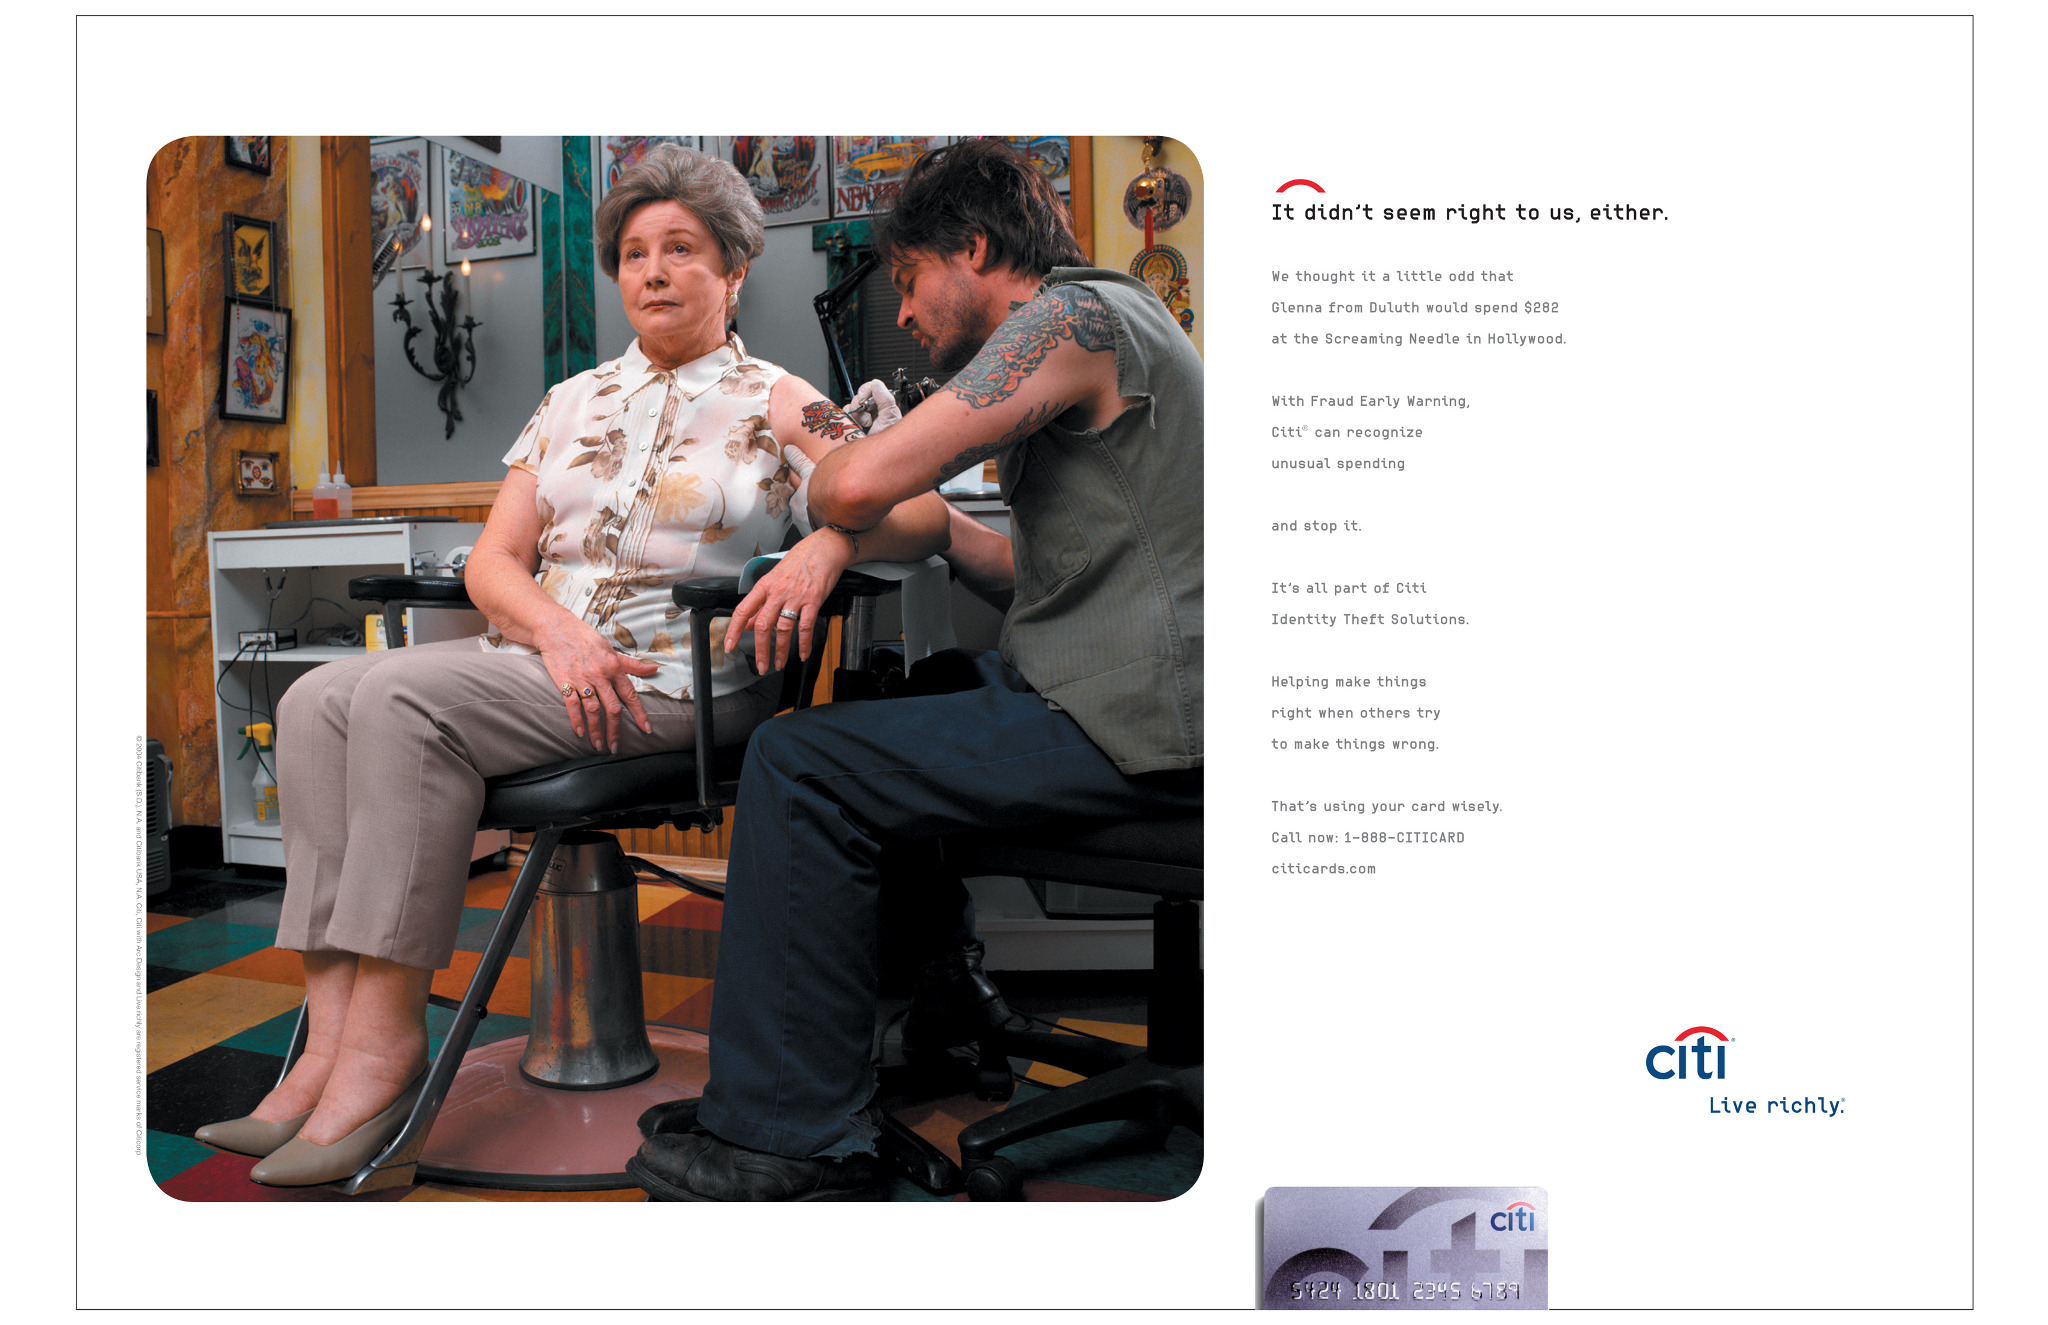
Ha-fucking-ha. Isn't that funny. Of course grams wouldn't get a tattoo. Thank God the nice bank people are saving her some trouble by shutting down her fucking card when someone uses it to get inked. Except they are only saving themselves trouble. Fraudulent charges were pretty much never a thing you personally would be on the hook for. But hey, the bean counters figured they could reduce the cost of shrinkage or whatever the fuck they call the provision to cover fraud, and get to bump up some sweet executive bonuses all for the cost of a snazzy PR ad campaign. "Well lookie that! People actually think we're doing them a favour by making it harder to use their credit cards. Hilarious !" And now, when grams goes to Mexico and buys gas - well fuck her. Or when a married guy buys a diamond for his lover - why not shut the card down so there can be some awkward questions at home. Ditto for the hobbyist that uses their card in an "unusual" way. So yeah. FUCK the banks. This is not needed, and makes my card - something I acquired so that I could use it any time, anywhere in the world for any reason, now something else. "Ah well, that's just the way it is now." Yeah. Well fuck them. Fuck them in the ear!
I travel a lot for business and personal. Quit fighting the banks a long time ago. Now I call them and tell them what state or country I will be in next week.

I travel a lot for business and personal. Quit fighting the banks a long time ago. Now I call them and tell them what state or country I will be in next week.
Even that doesn't work 100%, so be sure to bring enough info to be able to talk to your bank from wherever you are about your CCs. I'm no fan of the banks, but since it's them (and their insurance) that has to eat the loss you can't really blame them too much. Blame them for their fees, and fraudsters for being generally shitty people instead.

Damned right it is. I have a credit card. I signed up for one with the understanding that it was going to make it easier for me to make purchases, not harder. Then, somewhere around 15 - 20 years ago, some of their bean counters realised that they could lose fewer beans if they shut my credit card down for "suspicious activity". They even did a cute-funny ad campaign to get the mouth breathers on side:
Ha-fucking-ha. Isn't that funny. Of course grams wouldn't get a tattoo. Thank God the nice bank people are saving her some trouble by shutting down her fucking card when someone uses it to get inked. Except they are only saving themselves trouble. Fraudulent charges were pretty much never a thing you personally would be on the hook for. But hey, the bean counters figured they could reduce the cost of shrinkage or whatever the fuck they call the provision to cover fraud, and get to bump up some sweet executive bonuses all for the cost of a snazzy PR ad campaign. "Well lookie that! People actually think we're doing them a favour by making it harder to use their credit cards. Hilarious !" And now, when grams goes to Mexico and buys gas - well fuck her. Or when a married guy buys a diamond for his lover - why not shut the card down so there can be some awkward questions at home. Ditto for the hobbyist that uses their card in an "unusual" way. So yeah. FUCK the banks. This is not needed, and makes my card - something I acquired so that I could use it any time, anywhere in the world for any reason, now something else. "Ah well, that's just the way it is now." Yeah. Well fuck them. Fuck them in the ear!
Ok so I'll have put it this way.
It's NOT YOUR MONEY!
It's their money with an easy way to BORROW it. So they can get put whatever rules they desire to. And you can choose to or NOT to use this service. Don't like it. Pay cash. Pay debit. Take travellers checks. Whatever. But the onus IS on the Cardholder because it's NOT their money.
Ok so I'll have put it this way.
It's NOT YOUR MONEY!
It's their money with an easy way to BORROW it. So they can get put whatever rules they desire to. And you can choose to or NOT to use this service. Don't like it. Pay cash. Pay debit. Take travellers checks. Whatever. But the onus IS on the Cardholder because it's NOT their money.
A little due deligence and effort go a long way! I found out the hard way a few years back while vacationing in Europe. When I tried to use my CC, the transaction was denied. It took me a lot of work and effort to sort things out including calling the bank which issued the CC ( and not mentioning the stress level!). Nowadays, I could and would do it online easily to notify them (the banks) ahead of time where and when I will be while oversea - it really is no fuss no muss.

The travel thing's dragging us off Mable's topic, but before I let it go: Has anyone ever had any official written notice from their CC company—like a note on the statement or among the accompanying junkmail/spam that it's their policy to suspend cards without notice, if the card's used away from your home without their prior knowledge. Not me.I had a friend who did that. Someone in the bank told some accomplices who robbed his house. The police traced it back to the bank.
I'd even take a clause in the fine print as a " Yes". But as an example of all 'gimme' and 'the customer is always wrong', my flavour of VISA doesn't even have a "Press _ to warn us of/file your travel plans" option when you call.
Maybe the banks could allow the client to sign a waiver when they first get the card stating that they (the client) will be responsible and liable for all fraudalant transactions for those clients who are too lazy to notify the bank that they are traveling to Syria to join ISIS. That way the bank is off the hook and won't be wasting their time trying to track you down to ask if it was really you who purchased that RPG.A little due deligence and effort go a long way! I found out the hard way a few years back while vacationing in Europe. When I tried to use my CC, the transaction was denied. It took me a lot of work and effort to sort things out including calling the bank which issued the CC ( and not mentioning the stress level!). Nowadays, I could and would do it online easily to notify them (the banks) ahead of time where and when I will be while oversea - it really is no fuss no muss.
Banks (or more precisely, their clearing house processors) don't check for signatures, etc. Read the fine print of your bank/CC agreement. It's up to the customer to flag fraudulent transactions. If you do flag it, they'll investigate and (in my experience) reverse suspect charges.
CC systems are set up to detect anomalous patterns. If you usually get gas at the Shell station on your way to work and then suddenly get gas at the other end of town, an alert is raised. If your card is then used to buy a few hundred bucks of groceries and drop a grand at the sex shop, it will probably be flagged.
As for travelling, I don't call unless it's overseas. When flying, I usually use my main credit card to buy breakfast or whatever at the airport. When my next charge will be a rental car in, say Miami. So, when AMEX sees $1,800 at the Dirty Dancers Bar at Pervert's Beach, it ain't no thing....
CC systems are set up to detect anomalous patterns. If you usually get gas at the Shell station on your way to work and then suddenly get gas at the other end of town, an alert is raised. If your card is then used to buy a few hundred bucks of groceries and drop a grand at the sex shop, it will probably be flagged.
As for travelling, I don't call unless it's overseas. When flying, I usually use my main credit card to buy breakfast or whatever at the airport. When my next charge will be a rental car in, say Miami. So, when AMEX sees $1,800 at the Dirty Dancers Bar at Pervert's Beach, it ain't no thing....
Similar threads

- Replies
- 22
- Views
- 912


- Replies
- 0
- Views
- 96
